
Fitch Ratings has said that the meaningful performance disruption facing U.S. property/casualty (P/C) insurers in 2020 has dampened its expectations for additional profit improvement in the year.
 After consecutive years of consistent underwriting profitability, the P/C insurance sector in the U.S. started 2020 with record levels of capital and some positive pricing trends in commercial lines.
However, the outbreak of the ongoing, global coronavirus pandemic and subsequent financial market volatility and social and economic uncertainty, has altered the landscape for P/C insurers in the U.S., says Fitch.
In a new report, financial services ratings agency Fitch underlines widespread uncertainty for the sector around the duration and severity of the virus outbreak, the success of social distancing measures and lockdowns, and also uncertainty around potential longer-term effects.
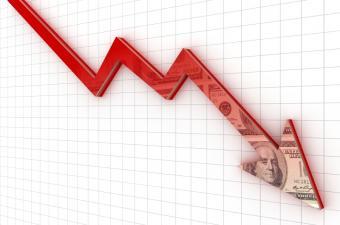
All of this uncertainty, says Fitch, makes it very hard to project what the financial implications might be for the U.S. P/C industry. However, analysts at the ratings agency do feel that the current crisis suggests P/C insurers’ anticipated profits for 2020 are trending lower.
“Previous expectations for further profit improvement in 2020 are now moving towards breakeven underwriting results and declining year over year earnings,” said Jim Auden, Managing Director.
As the coronavirus spread across Europe and beyond, driving the lockdown of numerous countries and serious impacts for individuals, businesses and entire industries, equity markets have declined significantly. Fitch notes that investment market volatility signals the most immediate impact for P/C insurers, with companies with larger allocations to this asset class expected to feel the impact.
However, insured losses from the coronavirus crisis and related economic disruptions are not expected to result in a sharp rise in loss ratios in 2020, adds Fitch.
“Claims are likely significant in some smaller specialty segments, including event cancellation and accident & health. Legal challenges to contract terms requiring physical damage for business interruption claims bears watching and could lead to some losses. Liability claims in several lines are also likely but will take some time to emerge,” the ratings agency explains.
Furthermore, premium volume in several lines might also suffer from reductions, while pricing momentum witnessed at the start of the year could fade as the economy trends downwards, says Fitch.