
Upstream energy market rates have remained stable, according to a new report by Gallagher.
 Despite rate rises, buyers can expect different treatment depending on the type and scale of coverage required.
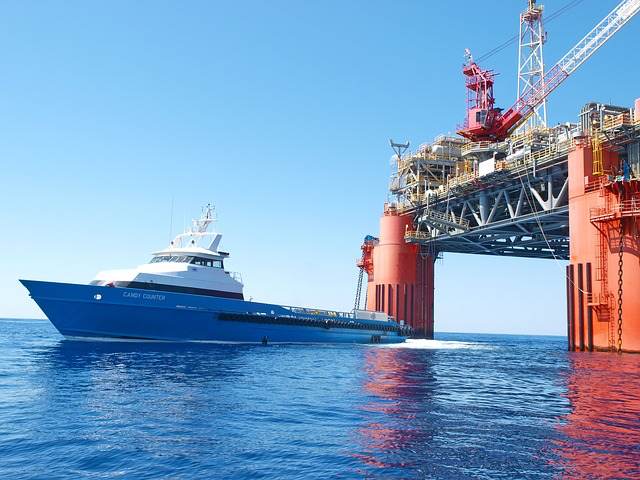
Offshore portfolio pricing for large national and international oil companies is either flat or experiencing modest increases, but Gallagher predicts that midmarket onshore portfolios may see high single-digit to low double-digit increases.
Loss of production income (LOPI) is being subjected to additional scrutiny, Gallagher finds. A few risks, including some stand-alone and smaller-scale assets, are attracting some of the highest rate rises.
There is still an abundance of excess capacity available, and capacity has increased, particularly for businesses with large-scale assets and good loss records. There were some rate reductions in late 2021, which have continued into 2022, particularly in sectors with more competition.
But clients looking to cover smaller-scale assets may face higher minimum premiums, as the market tries to maximise return on capital. Many underwriters are imposing minimum premium levels on small businesses or introducing artificial rate rises, as capacity is lower for this size of risk.
Gallagher says the market is preparing for a stronger year for premium levels – although the potential for losses is encouraging a focus on profit, not income.
Investor pressure around ESG (Environmental, Social and Governance) has lead to many clients are using carbon capture technology (CCS)as an alternative to conventional decommissioning, and as a means of generating extra revenue and to take advantage of associated tax breaks.
Insurers are generally prepared to cover these exposures, and CCS is likely to become an accepted element within the upstream portfolio, Gallagher says.